Knob-and-tube wiring affects homeowners insurance because carriers treat original, ungrounded branch wiring as a risk they want to price, limit or exclude. Each insurer sets its own rule. Some decline, some quote with conditions, some ask for an electrician’s assessment or a replacement deadline. Get your carrier’s exact requirement in writing before planning any work.
Philly Knob & Tube arranges knob-and-tube assessment and replacement for Philadelphia houses and small multifamily buildings, carried out by licensed and insured electrical contractors. This guide covers the insurance side in general: why the question gets asked, when it surfaces, what evidence answers it and what a homeowner controls. Narrower questions have their own pages, including whether a policy pays for the work and what to do when a carrier sets a date.
Why Carriers Ask About K&T
An insurer prices a house on how likely it is to produce a claim and how expensive that claim might be. Original knob-and-tube wiring raises underwriting questions for reasons that come from how the system was built and how it has aged.
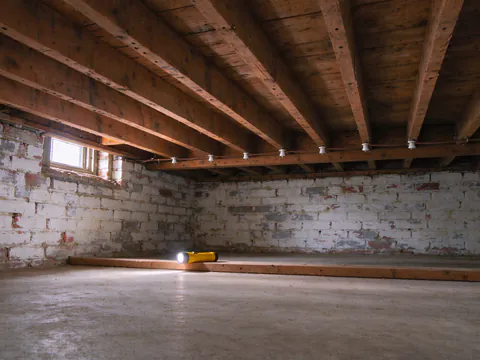
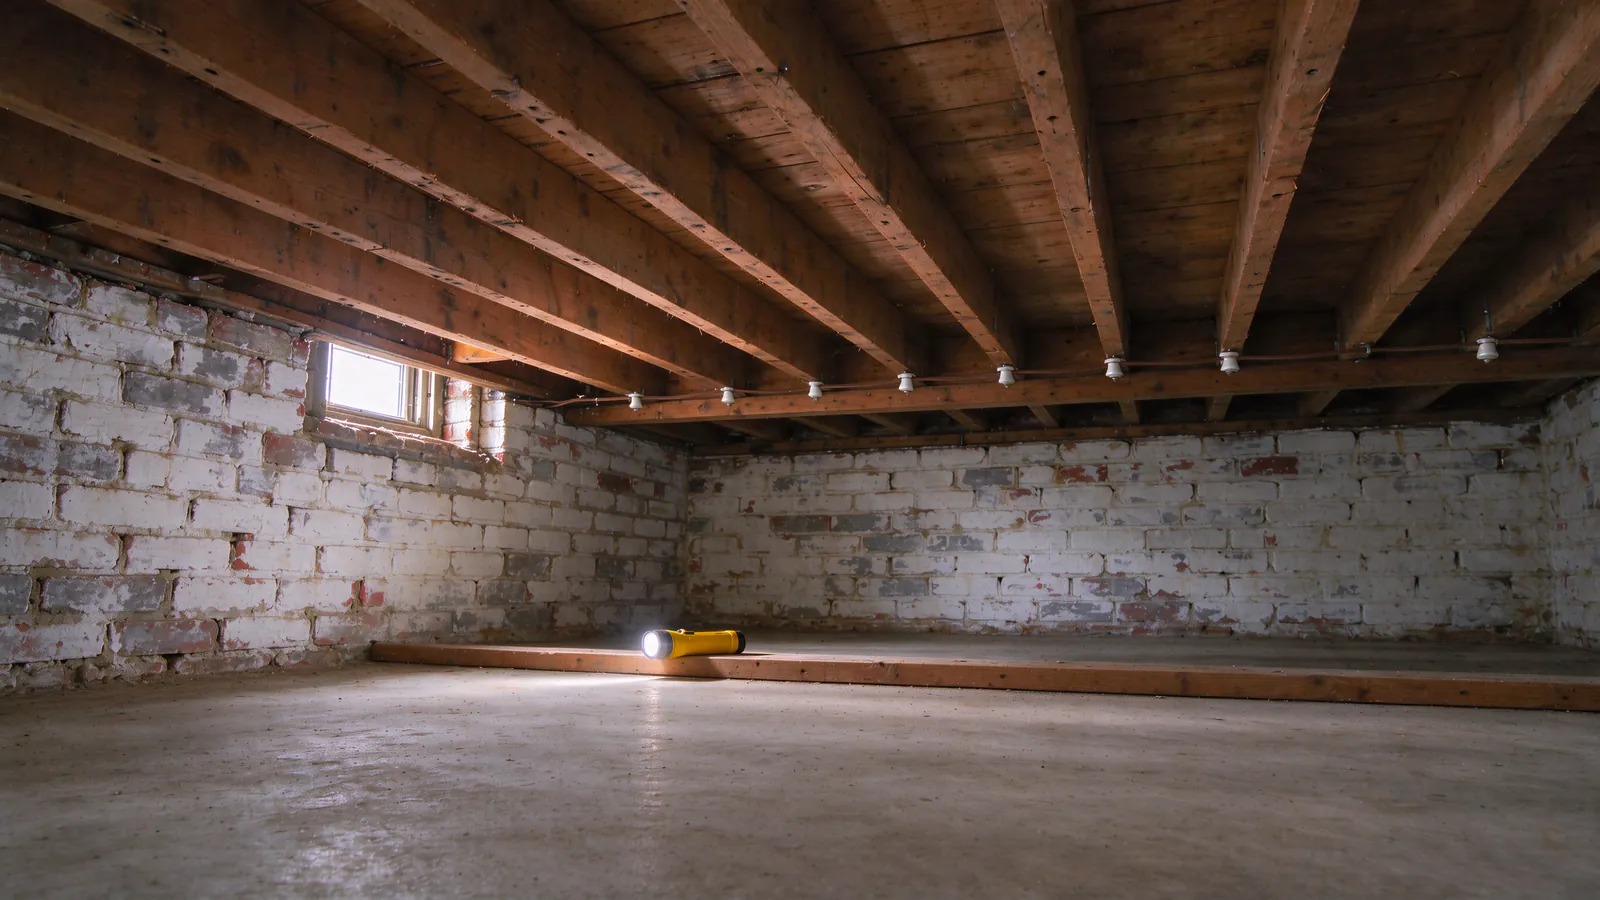
The conductors were designed to shed heat into open air, spaced apart on porcelain knobs and passed through framing in porcelain tubes. A century later, many of those runs sit under attic insulation that was never part of the design, and the rubber-and-cloth insulation on the wire itself can be brittle where it has been heated or handled. The system has no equipment grounding conductor, so modern three-prong devices and surge protection have nothing to bond to. Later owners often extended it with splices of uneven quality, and fuse boxes were sometimes fitted with fuses larger than the wire was meant to carry. The danger guide walks through each of those failure paths.
None of this means a particular house will burn. It means the underwriter cannot see the wiring, cannot tell how much of it still carries current and cannot judge the splices, so the uncertainty itself becomes the risk being priced. That is why a carrier’s question is often less about knob and tube as a material and more about whether anyone qualified has looked at it.
When the Question Comes Up
Homeowners report meeting the issue at four different points, and each one changes what you are being asked to do.
| Moment | What usually triggers it | What it tends to require from you |
|---|---|---|
| New application | A questionnaire item on wiring type, or the age of the house | An accurate answer, sometimes an electrician’s assessment before a quote |
| Renewal | Updated underwriting criteria or a new question on the renewal form | An answer, and possibly a condition with a date attached |
| Insurer inspection | An inspector photographs the panel, attic or basement | A response to the specific finding listed in the report |
| Home purchase | The buyer’s home inspection report mentions knob and tube | A quote that holds through settlement, covered in the buying guide |
The last row matters in Philadelphia because so much of the housing stock is old: the U.S. Census Bureau counts 39.9% of the city’s housing units, roughly 298,000 of 748,000, as built before 1940. That figure is context, not evidence about any one address. Plenty of prewar rowhouses were fully rewired decades ago, and some later houses carry knob-and-tube circuits extended from an older building next door or reused during a remodel.
An insurer inspection deserves a careful read. The inspector usually photographs what is visible from the basement, the attic hatch and the panel, and porcelain knobs left on a joist after the wiring was cut look exactly like knobs carrying a live circuit. If the report lists knob and tube that you have reason to think is dead, ask the carrier for the photos it relied on and whether an electrician’s circuit description would change the finding. A correction backed by a licensed contractor’s tracing is a different conversation from a homeowner’s recollection that “it was all redone years ago.”
Answer every application or renewal question truthfully. If the honest answer is “I don’t know whether it is still active,” that is a reason to get an assessment, not a reason to guess. The identification guide shows what the visible parts look like, and the online assessment helps sort how urgent your situation is before anyone visits. A wrong answer in either direction can cause trouble: overstating it may cost you a quote you could have had, and understating it can give the carrier grounds to dispute a later claim.
What an Electrical Assessment Establishes
An insurer wants facts it can rely on. A licensed electrician’s knob-and-tube inspection produces those facts by tracing circuits from the panel to the rooms and recording what each one is.
The most useful single output is a circuit-by-circuit description that separates four conditions. Active knob and tube is energized and feeding lights or outlets. Abandoned knob and tube has been disconnected at both ends and is dead, even if it is still in the walls. A partial system has some circuits replaced and others still original. A mixed system has new cable spliced into an old run, so a modern-looking outlet still depends on knob and tube upstream. The active versus abandoned guide explains how an electrician tells them apart.
Those categories line up closely with the questions carriers ask. “Is there knob and tube in the house?” and “Is any knob and tube in service?” have different answers in a house where every original run was cut at the panel twenty years ago. An assessment lets you answer the question the carrier actually asked.
An assessment also has limits that belong in the record. Runs inside closed plaster walls can be inferred from where they start and end, but not seen along their length. A written description that says “no active knob and tube found on the circuits traced; concealed sections in the second-floor walls not observed” is more useful to an underwriter than a broad statement that nobody could stand behind.
What a Homeowner Controls
You cannot control a carrier’s underwriting rules, and no electrical work guarantees that a specific insurer will accept the house afterward. You do control several things that shape how the conversation goes.
The accuracy and timing of your information. Getting an assessment before a renewal date, rather than after a notice arrives, turns a reactive scramble into a planned project.
The scope you choose. Replacing only the circuits a carrier flagged may satisfy one insurer and not another. Whole-home replacement removes the question entirely for the active wiring but costs more and takes longer. The partial versus full guide covers that tradeoff.
Which carriers you approach. Homeowners report that rules differ sharply between companies. An independent agent who places policies with several insurers can find out which ones will quote a house with disclosed original wiring, and under what conditions, without you applying blind to each.
The paperwork you keep. Permit numbers, inspection records and an electrician’s description of the finished scope are what a future underwriter, a buyer’s insurer or a claims adjuster will ask for. The removal letter guide explains what those documents should say.
Questions to Ask Your Insurer
Verbal answers from a call center can change from one call to the next, so ask for the requirement in an email or letter. These questions pin it down:
- Is the concern any knob and tube present in the house, or only knob and tube that is still energized?
- Does disconnected, abandoned wiring left in the walls satisfy the requirement?
- Would replacing specific circuits be enough, or does the requirement cover the whole house?
- What proof do you accept: an electrician’s letter, a permit record, a final inspection report, photos, or a form of your own?
- Must the electrician’s statement include a license number or particular wording?
- Is there a date, and does it apply to finishing the work or to submitting proof?
- Does the requirement affect the current policy term, the renewal, or both?
The answers decide what to ask the electrician for. If the carrier only cares about energized wiring, a circuit map plus disconnection of dead runs at both ends may be the right first step. If it wants all original wiring replaced, the scope and budget are different, and the Philadelphia cost guide gives the planning range and what moves it.
Planning Work Without Promising Approval
Treat the insurer’s requirement as one input to a wiring plan, not the whole plan. A carrier’s request may cover two circuits while the assessment shows that a third, unflagged circuit has heat damage at a splice. The electrical findings decide what is safe to leave; the insurer’s letter decides what it will accept as proof.
In Philadelphia, replacing branch wiring is permitted work. A licensed electrical contractor applies through L&I’s eCLIPSE system, and a licensed third-party electrical inspection agency inspects the rough-in before walls close and the finished work after. Those records exist whether or not an insurer asks for them, and they are the strongest evidence you can offer later. The permit guide covers that process.
When you request an estimate, share the insurer’s written requirement so the scope can be written in the same terms. Then send the carrier the proposal before work starts and ask whether it would satisfy them once complete. If they will not say, you have learned something useful about the risk of relying on that carrier, and you can decide whether to shop the policy while the work is planned. When you are ready to describe the house and the carrier’s request, the contact page is the place to start.